Ditch: Pay Off Debt Faster
Ditch Technologies, IncFinanceVerified
- 20.00 Reviews
- 4.3
- Downloads
- 10,000+
- Price
- Free
Screenshots


 Analysis by Appwesome
When I choose a debt app, I want more than a colourful balance screen: I need a practical way to see what I owe, decide what to tackle next, and keep the plan visible when daily spending competes for attention. Ditch: Pay Off Debt Faster is aimed at that focused job. It is a free finance app from Ditch Technologies, Inc, and its emphasis is on organising repayment rather than trying to replace every money tool on my phone.
That focus is useful, but it also shapes who should consider it. If you have several balances and feel unsure how to make progress, a dedicated payoff tracker can turn an abstract problem into a sequence of choices. If you mainly need a household budget, bill calendar, or complete picture of your spending, a broader finance app or a spreadsheet may suit you better. I would decide based on whether debt repayment is the problem I want to work on right now.
What to decide before entering your balances
Before setting up any repayment plan, I would gather current balances, minimum payments, interest rates, and due dates. The more accurately I enter those details, the more useful any payoff estimate or progress display can be. I would also check statements after a new transaction or payment, rather than trusting an old figure to stay current. That small habit matters: a clear tracker is only as helpful as the information behind it.
A realistic use case is a payday routine. I could open the app after checking my account, update a card balance after its payment posts, then review the next debt target before deciding how much extra I can afford to pay. The important step is to keep essentials and minimum payments covered first; a motivating payoff goal should not encourage me to leave too little for rent, food, or an unexpected expense. For that reason, I see the app as a planning aid, not a substitute for a budget or personal financial advice.
Who gets the most from a debt-first approach
Ditch is most relevant to someone who already knows their main problem is outstanding debt and wants a visible route through it. It can help make a long-term goal feel manageable by breaking attention down to the next balance and the next payment. That is different from promising that a particular app can change someone’s finances by itself; the useful part is the routine it may help you maintain.
There is also a practical trade-off in choosing a debt-first method. The snowball approach focuses extra payments on the smallest balance while minimums continue elsewhere, which can create an early sense of progress. But the smallest balance is not necessarily the most expensive one to carry. If minimizing interest is the priority, compare the snowball with an approach that directs extra money to the highest-rate debt first, and decide whether faster visible wins or lower borrowing costs matter more to you.
Where a spreadsheet or broader finance app may fit
Many people manage repayment with a spreadsheet, notes, or a general budgeting app. Those options can be more flexible: you can track spending alongside debts, add categories that matter to your household, or build your own calculations. The trade-off is that you have to maintain the system yourself. A focused app may feel easier to return to when all you want is a debt plan, while a spreadsheet may be a better fit if you like controlling every formula and field.
Other Stories to Read




I would also be careful about treating reminders or progress visuals as a complete financial system. A debt tracker can help me remember a target, but I still need to confirm that a payment was made through the lender and that it posted correctly. Anyone whose income changes month to month may want to review the plan whenever their available amount shifts, rather than following a fixed extra-payment target automatically. That review keeps motivation from turning into an unrealistic commitment.
Getting Started with Ditch
Jumping into Ditch: Pay Off Debt Faster is as easy as pie. Once you download and fire up the app, it greets you with a clean and intuitive interface. This is crucial for an app dealing with finances; nobody wants to navigate through a cluttered mess when they're already stressed about money!
The initial setup is straightforward. You input your debts, such as credit cards, student loans, or any other looming payments you might have. The app then creates a personalized plan tailored to your financial situation and goals. It’s almost like it takes a deep breath for you, saying, “Don’t worry, we’ve got this.”
Features That Stand Out
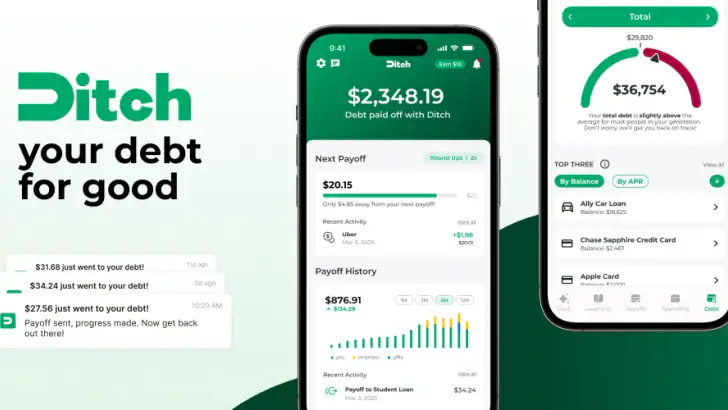
One of my favorite features is the ability to visualize your debt payoff journey. The app provides a clear timeline and progress tracker, which can be super motivating. Seeing how each payment brings you closer to your goal is like watching the finish line get a little bit closer with every step.
The app also uses the debt snowball method, which is a popular strategy where you pay off smaller debts first, gradually working towards larger ones. It’s a psychological boost, giving you quick wins and keeping your motivation high. Trust me, those little victories add up quickly!
Keeping the plan useful over time
One less obvious benefit of a progress view is that it can help me spot when my plan has drifted away from real life. If I make an extra payment, miss a planned amount, or take on a new balance, I should update the figures instead of judging myself against an outdated timeline. I would use the tracker as a checkpoint, not a scoreboard: its job is to help me choose a sensible next step, not make a difficult month feel like failure.
A useful habit is to separate the minimum due from any extra payment I hope to make. I would first confirm the minimums and due dates with each lender, then treat extra money as optional until essentials and a cash cushion are accounted for. This makes a snowball plan less brittle. If an unexpected bill arrives, I can pause extra repayment without losing sight of the balances or confusing a temporary change with giving up.
Why It’s Different
There are plenty of financial apps out there, yet what sets Ditch apart is its focus on debt elimination. Many apps try to do everything—budgeting, saving, investing—but Ditch: Pay Off Debt Faster hones in on one thing and does it well. It’s like having a personal trainer for your finances, focused solely on getting you debt-free.
The app’s notifications are a lifesaver. They remind you of upcoming payments and keep you accountable without being intrusive. It’s like having a little nudge that says, “Hey, remember your goal?” without being all up in your face about it.
Questions I would settle before relying on it
Would I still need to pay lenders separately? Yes: I would regard the tracker and its plan as guidance, then make payments through the lender’s usual channel and verify that each one posts. Does the plan remove debt automatically? I would not assume so; the useful workflow is to enter accurate balances, follow the intended payment strategy, and keep records aligned with lender statements.
What if my income or expenses change? I would revisit the numbers and adjust what I can safely put toward extra payments. What if I have only one debt? The visual plan may still help me stay focused, but the app’s debt-first emphasis is less compelling if I need a full monthly budget more than a payoff sequence. These are good questions to ask before making any finance tool part of a regular routine.
For Android users, the app is rated for Everyone, has an average rating of 4.3 from 126 ratings, and has passed 10K+ installs. It was released on September 12, 2023, and version 1.4.5 requires Android 8.0 or later. Those details suggest a modestly established option rather than a brand-new experiment, though I would still judge it by whether its workflow suits my own habits. The app is free to download, with in-app purchases listed from $8.99 to $89.99 per item, so I would check any purchase details in the app before committing to paid features.
Real-Life Impact
Now, let’s talk about how this app can actually change your life. By sticking to the plan laid out by Ditch, you’re not only working towards paying off debt but also improving your credit score. And with better credit, you open up a world of financial opportunities, like lower interest rates and better loan terms. It’s a ripple effect that starts with a single decision to tackle your debt head-on.
Users have shared stories about how the app helped them reclaim their financial freedom, and that’s no small feat. Imagine being able to allocate your income towards things you’re passionate about instead of just making ends meet. That’s the kind of empowerment Ditch aims to deliver.
When I would choose something else
I would skip a dedicated payoff app if my biggest difficulty is not knowing where my money goes each month. A full budgeting tool can connect everyday categories to repayment decisions, while a spreadsheet can make it easier to test different payment priorities side by side. Someone carrying high-interest balances may also prefer to compare payoff strategies carefully instead of assuming that the snowball’s quick wins are always the cheapest route.
There is a switching cost to consider, too. Moving from a spreadsheet or another tracker means re-entering balances and checking that each account is represented correctly. I would do that once with statements open, then keep the old record until the new plan matches it. If I later leave Ditch, I would preserve my own balance and payment notes rather than relying on memory. That simple record-keeping avoids turning a change of tool into a gap in the repayment routine.
Final Thoughts
In a world where debt can feel like a heavy weight on your shoulders, Ditch: Pay Off Debt Faster offers a light at the end of the tunnel. It’s user-friendly, effective, and most importantly, it keeps you motivated. Whether you’re drowning in loans or just looking to pay off a few credit cards, this app could be the key to unlocking a debt-free future.
So, if you’re ready to take control of your financial destiny, give Ditch a try. It might just be the best decision you ever make for your wallet—and your peace of mind.
My recommendation
I would try Ditch if I wanted a focused place to organize several debts, found the snowball method motivating, and was willing to keep its figures current. The free download makes it possible to assess the basic fit before deciding whether any in-app purchase is worth considering. I would not treat a rating, a timeline, or a reminder as proof that a payoff plan is right for me; I would check the numbers against my statements and make sure the monthly amount remains realistic.
For someone who wants a clear repayment routine more than an all-purpose money manager, this is a sensible app to consider. If I needed detailed spending analysis, complete control over calculations, or a strategy centered on reducing interest rather than celebrating small balances first, I would compare it with a budget app, a spreadsheet, or guidance suited to that goal. Its strongest case is simple: it can help keep debt repayment in view, as long as I remain the one making informed decisions.
Highlights
- User-friendly interface for easy navigation.
- Customizable payment reminders.
- Detailed progress tracking charts.
- Supports multiple debt types.
- Syncs with your bank accounts for accuracy.
Limitations
- Limited features in free version.
- Occasional syncing issues with banks.
- Ads can be intrusive at times.
- Initial setup can be time-consuming.
- No offline mode available.
Frequently Asked Questions
01What is Ditch: Pay Off Debt Faster?
Ditch is a personal finance app designed to help users manage and pay off their debts more efficiently. By consolidating debt information in one place, it provides personalized plans and strategies to accelerate debt repayment. The app also offers features like payment reminders and progress tracking to keep users motivated.
02How does Ditch help in paying off debt faster?
Ditch employs algorithms to analyze your debt and financial situation, creating a customized repayment plan. It prioritizes debts based on factors like interest rates and payment schedules, helping you focus on paying off high-interest debts first. Additionally, it provides tips and reminders to ensure timely payments, preventing additional fees.
03Is my financial information safe with Ditch?
Yes, Ditch prioritizes user privacy and security. The app uses advanced encryption methods to protect your financial data. It does not share your information with third parties without consent. Users can also enable security features like PIN codes or biometric authentication for added protection.
04Can Ditch handle multiple types of debts?
Absolutely. Ditch is designed to manage various types of debts, including credit card debts, student loans, mortgages, and personal loans. By inputting all your debt details, the app provides a comprehensive overview and a unified plan to tackle each debt effectively, helping to streamline your repayment process.
05Is Ditch suitable for everyone?
Ditch is ideal for anyone looking to organize and pay off their debt more efficiently. However, it may be most beneficial for individuals with multiple debts or those struggling to keep track of payment schedules. Users seeking basic budgeting tools might need additional apps, as Ditch focuses primarily on debt repayment.


